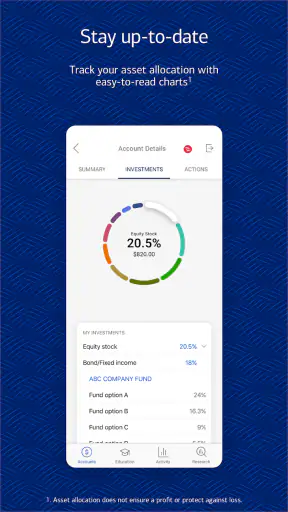
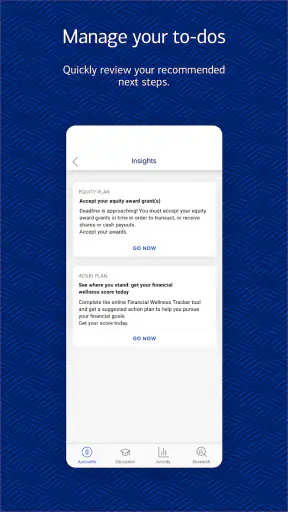
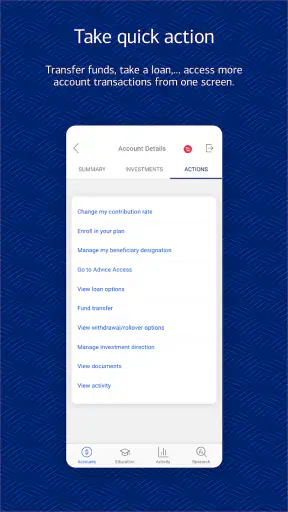
I found Benefits OnLine most useful as a focused companion for people whose retirement or workplace benefit information is handled through Merrill Lynch, Pierce, Fenner, and Smith Inc. It is a finance app rather than a general budgeting tool, investment-learning platform, or everyday banking replacement. That distinction matters: the app’s value depends heavily on whether your employer or plan already connects you to the service.
The app is free to install, carries an Everyone content rating, and is listed for Android devices running version 11 or later. I would not approach it expecting a broad personal-finance dashboard. Its purpose is narrower and more practical: giving eligible users a mobile route to their retirement and benefit services instead of making every check require a desktop browser.
How Benefits OnLine fits into retirement and benefit management
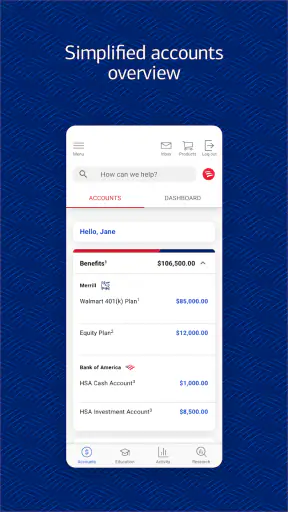
In my experience, the strongest reason to use this app is convenience around information that people often check only occasionally. Retirement contributions, workplace benefits, and plan-related details are not usually things I want mixed into a spending tracker or a banking app. Keeping that information in a dedicated place can make it easier to separate long-term planning from daily transactions.
The developer is Merrill Lynch, Pierce, Fenner, and Smith Inc., and the store summary identifies the service as retirement and benefit services provided by Merrill Lynch. That tells me who the app is intended for, but it also sets an important boundary. This is not an app I would recommend simply because someone wants to begin investing or organize household bills. It makes the most sense when your benefits relationship already points you toward Merrill’s online service.
The app has been available since October 1, 2018, and its current version is 26.08.02. Those details suggest an established mobile service rather than a newly launched experiment, although an older release history alone does not guarantee that every screen will feel modern. The store shows over a million installs, with an average rating of 3.5 from around 3.4 thousand ratings. I read that as evidence of meaningful use, but not as a reason to ignore the mixed experience implied by the middling score.
That rating is especially relevant for a benefits app. A finance tool can be judged on design and speed, but access reliability matters just as much. If I am checking a retirement account during an enrollment period or trying to understand a workplace benefit, a confusing sign-in path or an unclear status message creates more frustration than it would in a casual entertainment app.
What the free price really means
There is no purchase price for downloading Benefits OnLine. That makes the initial decision simple: eligible users can try it without paying for the app itself. Still, “free” should not be confused with universal access or with a complete financial service at no cost. The app’s usefulness comes from the benefit relationship behind it, not from unlocking a standalone collection of planning tools.
I would therefore judge the price in two layers. The first is direct cost, and on that point the app is accessible. The second is practical value: whether it saves enough time and effort compared with using a browser, paper documents, or an employer’s benefits portal. If your plan is supported and you regularly need account information, free mobile access can be worthwhile even if you open the app only a few times each year.
For someone without a connected Merrill benefit account, the free download offers little reason to remain installed. It is not the kind of finance app that becomes useful merely because I have a bank account or want to monitor general spending. That is the first trade-off to understand before downloading it.
Where the app can save time
The clearest everyday scenario is a change in employment. Imagine I have just started a new job and need to review retirement enrollment details, check whether my contribution choice is reflected, or revisit information about workplace benefits. A mobile app can be more convenient than searching through old email, locating a company portal, and remembering which page contains the relevant account information.
A second useful situation is a quick check away from a desk. I might be discussing household planning with a partner, reviewing a benefits document before making a decision, or trying to confirm information while commuting. I would still make important financial choices carefully, but having a dedicated mobile entry point reduces the friction of finding the right service.
The less obvious benefit is organizational rather than flashy. Retirement information often gets scattered across employer messages, annual documents, and separate websites. A dedicated service can give me a consistent place to begin. That does not replace reading plan documents, but it can make the first step less intimidating, particularly when I only need to orient myself before taking a more serious look.
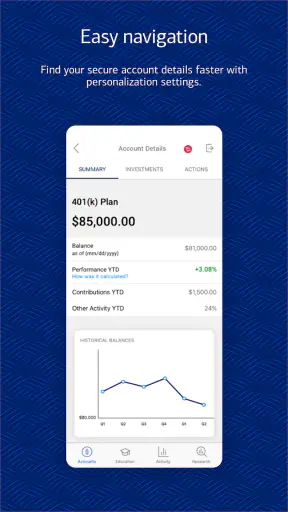
My practical tip is to treat the app as a checking and access tool, not as the sole source of financial understanding. Before changing a contribution or making a benefits decision, I would compare what I see in the app with the relevant plan material and any employer instructions. Mobile convenience is valuable, but a small screen is not always the best place to interpret complicated terms.
What it does better than general finance alternatives
Compared with a budgeting app, Benefits OnLine has a different center of gravity. Budgeting apps are usually built around spending categories, bank transactions, cash flow, and monthly habits. That is useful for controlling day-to-day money, but it can leave workplace retirement information feeling disconnected. This app is the better fit when the question is about a benefit plan rather than where last month’s money went.
Compared with a general brokerage app, it is also more specialized. A brokerage platform may be preferable for people who want to research investments, manage a broad portfolio, or bring multiple account types together. Benefits OnLine is more appropriate when the employer-sponsored benefit relationship is the starting point and I want a direct way to reach that information.
The browser version of a benefits portal may still be better for extended sessions. A larger screen is easier for comparing documents, reading detailed explanations, or working through several sections without repeatedly navigating back. I see the mobile app as the quick-access layer: useful for routine checks and convenient moments, while the full website may remain the better workspace for careful review.
That division of labor is one of the most realistic ways to use it. I would not force a phone app to replace every desktop task. Instead, I would use mobile access to remind myself what needs attention, then move to the larger interface when a decision requires concentration.
Small workflow choices that improve the experience
One useful habit is to open the app before an important deadline rather than waiting until the final day. Benefits tasks can involve several steps, and discovering an access problem at the last minute is much more stressful than finding it early. Even when I only intend to review information, an advance check gives me time to switch to the browser or contact the appropriate support channel if necessary.
Another is to keep a short personal note about what I wanted to verify before opening the app. Retirement and benefits screens can contain several balances, elections, or status details, and it is easy to leave without answering the original question. Writing down a simple goal—such as checking enrollment status or locating a plan document—makes a short mobile session more productive.
I also recommend separating “information gathering” from “decision making.” On a phone, I might confirm that a detail is available, save the relevant wording for later reference, and then review the implications on a larger screen. That approach reduces the risk of making a rushed change simply because the app makes access convenient.
Finally, I would avoid judging the service only by how often I use it. A retirement app may be valuable precisely because it is there when a job change, enrollment period, or benefits question arises. Low daily engagement is not automatically a weakness for this category. The better question is whether it gives me dependable access when that occasional need appears.
Where the experience may feel limited
The narrow purpose is also the main limitation. If I want one application for spending, saving, credit monitoring, investment research, and retirement planning, this is unlikely to satisfy me on its own. I would need other tools for those jobs, and switching between services can make my overall financial picture feel fragmented.
The average rating of 3.5 indicates that the experience is not universally smooth. I would take that as a reason to keep expectations measured, especially if mobile access is essential to my benefits routine. A dedicated app can be convenient, but convenience disappears quickly when sign-in, navigation, or account visibility does not work as expected.
There is also a difference between seeing account information and understanding it. A balance or enrollment status may answer a narrow question, but it does not automatically explain fees, investment choices, tax implications, vesting, or the consequences of a change. I would not use the presence of a mobile interface as a substitute for official plan explanations or professional advice when the decision is significant.
People who manage several employers’ plans may find a single-provider benefits app less convenient than an independent financial organizer. Consolidation can be more important than direct access for that audience. If my main goal were to view every retirement account in one place, I would first compare whether a broader alternative supports that workflow more effectively.
Device compatibility is another practical checkpoint. The listed minimum is Android 11, so anyone using an older Android device should check compatibility before planning around the app. For supported users, that requirement is reasonable, but it still means the app is not suitable for every phone in circulation.
Who is most likely to get real value
I would recommend trying Benefits OnLine to an employee, former employee, or plan participant whose retirement or workplace benefits are administered through the Merrill service. It is particularly useful for people who dislike hunting through desktop portals and want a direct mobile starting point for occasional account checks.
It may also suit someone who is organized but busy. A person who already understands the basics of their plan can use a quick mobile visit to confirm information, then reserve deeper research for a quieter moment. In that role, the app is a practical access tool rather than a teacher or financial coach.
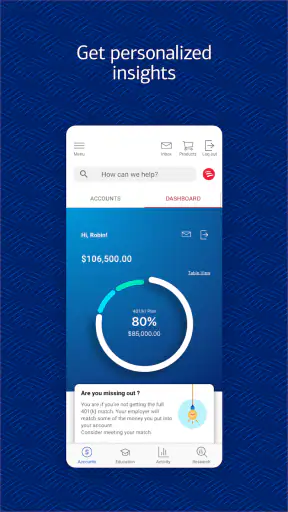
New employees may benefit from having it available during the early stages of understanding workplace benefits. I would still read the employer’s enrollment material carefully, because an app can show the service but cannot replace the choices and deadlines explained in those documents. The best workflow is to use the app for visibility and the official plan material for context.
People who should probably skip it are those looking for a general budgeting solution, a broad investment marketplace, or a unified dashboard for unrelated financial accounts. They may download it because it appears in a finance category, only to discover that its value is tied to a specific benefits relationship. In that case, a budgeting app, brokerage platform, or independent retirement organizer would be a better first choice.
My verdict on keeping it installed
My view is positive but conditional. Benefits OnLine earns its place on my phone when I am connected to a supported Merrill workplace or retirement plan and want a convenient alternative to repeatedly opening a browser. The free price removes the financial risk of testing it, and the service’s established presence gives it more credibility than an unfamiliar new finance app.
At the same time, I would not describe it as a complete personal-finance solution. Its value is concentrated in retirement and benefit access, and the middling average rating reminds me that the mobile experience may not be flawless for everyone. I would keep a browser-based fallback and use a larger screen for complicated decisions or detailed document review.
My bottom line: download it if your Merrill benefit plan makes it relevant, but skip it if you need general money management. The app is most convincing as a free convenience layer for an existing relationship. It does not need to do everything to be useful; it simply needs to make those occasional retirement and workplace-benefit tasks easier to reach. For the right user, that is a sensible reason to install it. For everyone else, the lack of broader financial coverage makes another category of app a better match.


